C.V. Starr & Co. Lecture on China With Dan Wang
Event date
Speaker
- Research Fellow, Hoover Institution; Author, Breakneck: China’s Quest to Engineer the Future
Presider
- Rush DoshiCFR ExpertC.V. Starr Senior Fellow for Asia Studies and Director of the China Strategy Initiative, Council on Foreign Relations
Dan Wang, author of Breakneck: China’s Quest to Engineer the Future, and research fellow at the Hoover Institution, discusses long-term competition between the United States and China.
The C.V. Starr & Co. Lecture on China was established in 2018 to honor the trailblazing career of C.V. Starr and the Chairman and Chief Executive Officer of C.V. Starr & Co., Maurice R. Greenberg. This meeting is presented in partnership with CFR’s China Strategy Initiative.
DOSHI: Well, good afternoon, everybody. My name is Rush Doshi. Welcome to the Council on Foreign Relations.
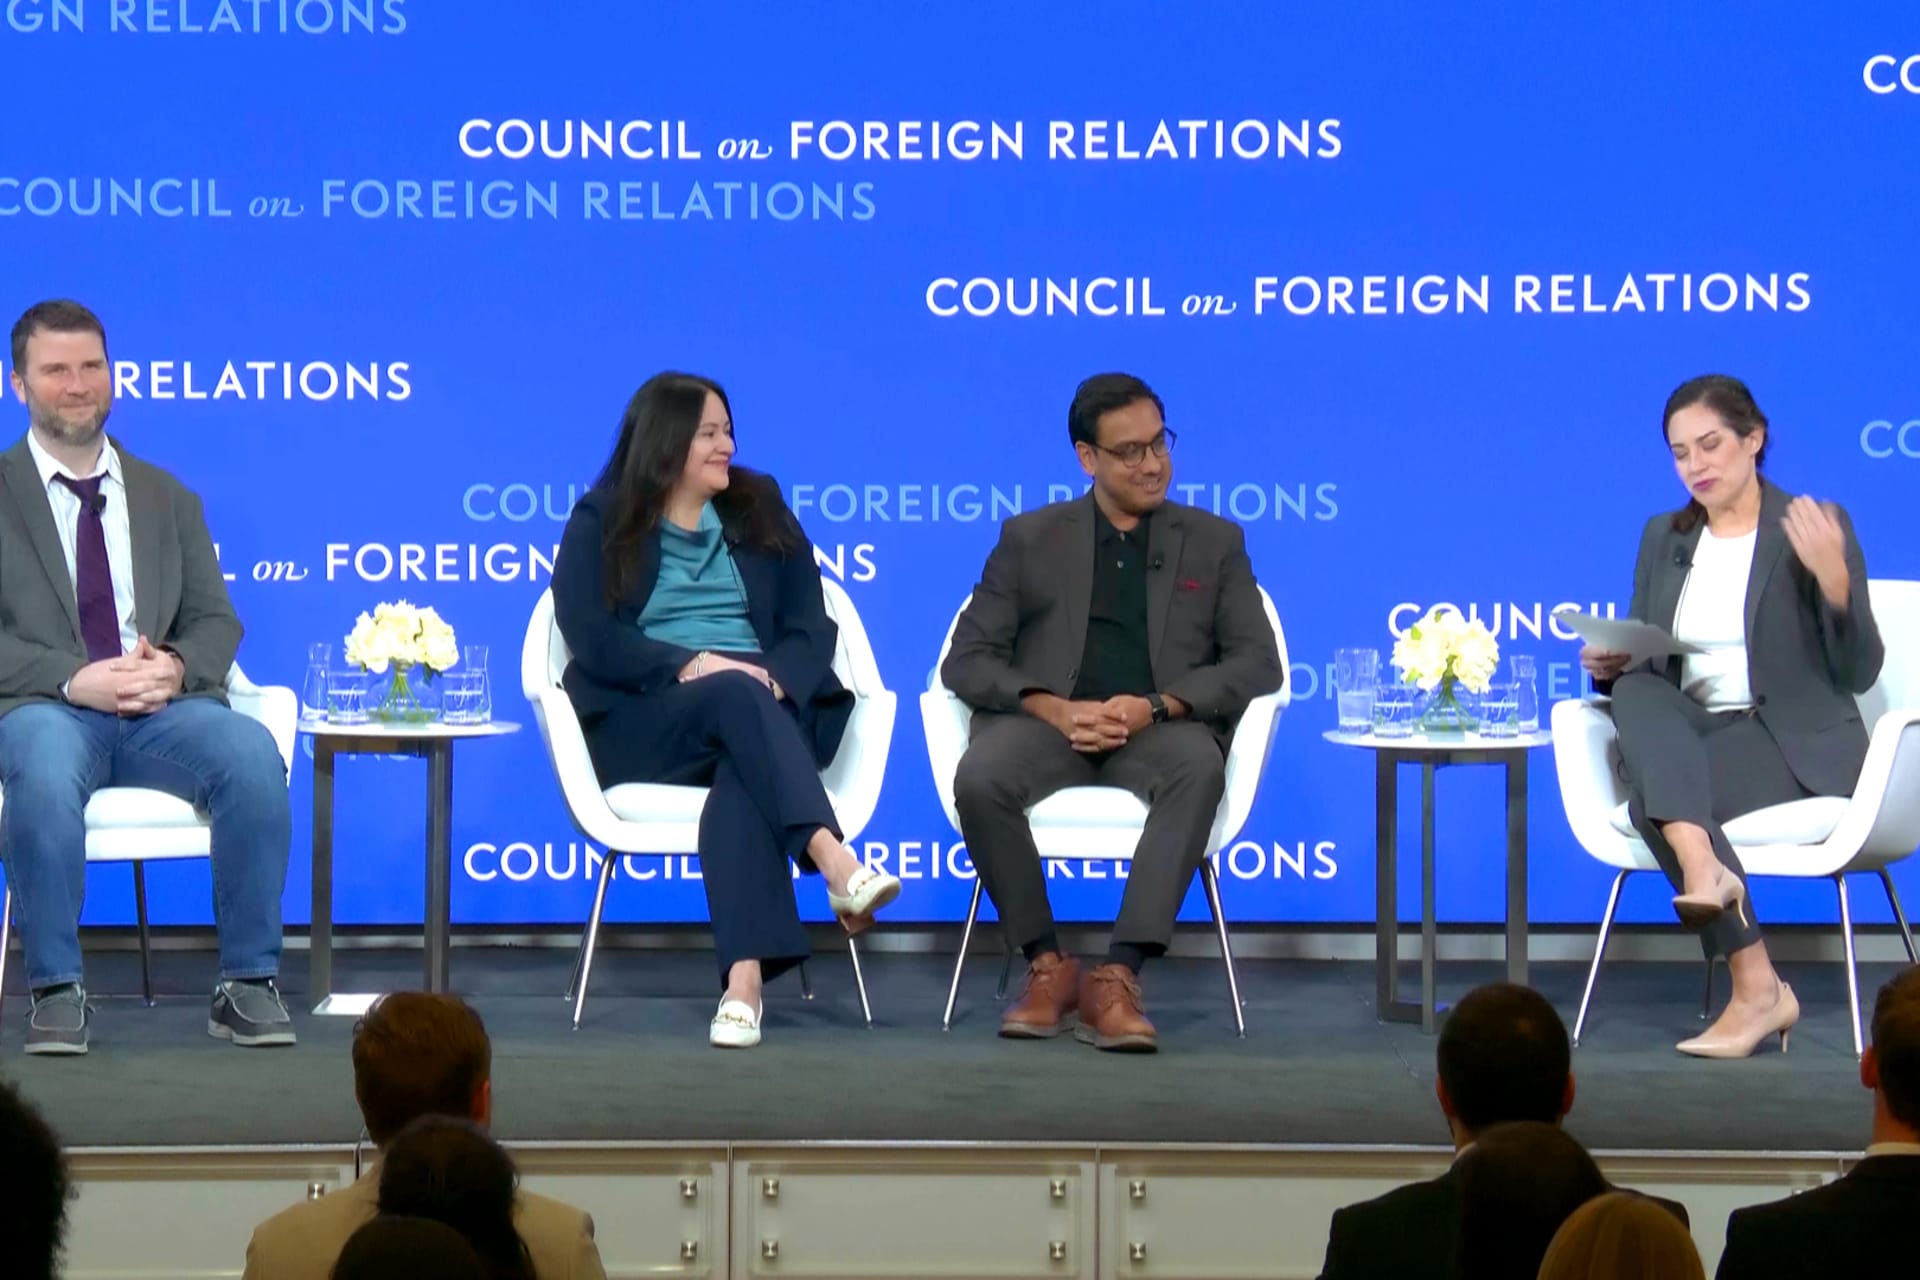
I’m excited to welcome you all to the annual C.V. Starr & Co. Lecture on China, delivered today by our distinguished speaker Dan Wang. Now, Dan has graciously allowed us to dispense with the usual lecture so we can have a kind of back and forth conversation that I think will be more to everybody’s interest.
A bit about this series. This series was established in 2018 to honor the career of C.V. Starr and the chairman—he was the chairman and chief executive—excuse me—and to honor the chairman and chief executive of the C.V. Starr Company, Maurice, or Hank, Greenberg. We’re thrilled to welcome almost 120 people in this room and more than 300 online for this fantastic event. Today’s lecture is also part of the CFR China Strategy Initiative, one of our crosscutting initiatives here at the Council. And particularly relevant to today’s lecture, one of the important pillars is sort of the sources of American competitiveness vis-à-vis China in economic, industrial, and technological parameters.
And there’s no one, I think, better to help us understand that question and how to navigate it than Dan Wang, the author of a book I think all of you have read, a New York Times bestselling book, Breakneck: China’s Quest to Engineer the Future, and also a finalist for the Financial Times Schroeder Business Book of the Year as well. He’s a research fellow at Stanford’s Hoover Institution. He was previously at the Yale Law School’s Paul Tsai China Center. And Dan was based in China for almost six, seven years as a technology analyst as well, from 2017 to 2023, where he wrote a widely circulated annual letter on China that many of you probably had a chance to read at various points. His essays have appeared in every outlet you can imagine.
Again, I’m sure many of you have read the book, and today we’ll talk about the book, but we also want to go beyond the book. The book was largely written, I think, in 2024. Came out in 2025. But the world has changed a bit since then. So Dan will update some of the arguments of the book, and we’ll have a conversation not just about the past, but also the future of U.S.-China and techno-industrial competition.
In terms of the run of show, Dan and I will have a conversation for about thirty minutes, and then we’ll turn to the audience for the remainder of the lecture. We’ll have Q&A. There’ll be folks with microphones who you can provide your question—they’ll give you the microphone when you have a question. We have folks online who you can join the discussion as well if you raise your hand and offer the question to. So with that, I think we’ll turn to the discussion right away to save time. And maybe, for the benefit of everybody in the room and online, and especially those who haven’t yet read the book, could you just maybe outline for us sort of the main argument of the book?
WANG: It’s a delight to be here, Rush. And it’s—we promise that we will try to keep this fun and lively.
DOSHI: We’ll try.
WANG: I want to have as much of a conversation as possible.
So I spent six years looking at China’s technology development, at a time when it was surging forward in terms of a lot of its capabilities—electric vehicles, semiconductions, industrial robotics, et cetera. And I was also living in China throughout zero COVID. I was there for the entire three years. And after seeing how these things sort of work, I wrote about China in Breakneck, as the country I call “the engineering state,” because at various points in the recent past all nine members of the standing committee of the Politburo—which is the highest-ruling echelon—all of them had degrees in engineering. And this was engineering of a very soviet sort. So they were hydraulic engineers, geologists, electrical engineers, et cetera.
The issue with engineers is the kind of build their way out of any of their problems. And so this is why we have these giant construction projects involving housing, solar, coal, nuclear, wind, high-speed rail, bridges, roads, et cetera. These are all the things that we can see. We also have the one-child policy as well as zero COVID, in which the number is right there in the name. There’s no ambiguity about what these things could possibly mean. And so they are not just physical engineers. They’re also social engineers, population engineers, engineers of the soul, which is a phrase from Stalin that top leader Xi Jinping has repeated.
Then at the start of 2023, I moved to the Yale Law School, where I was a fellow at the Tsai Center, where, Rush, you’ve also that’s right spent a bit of time. And Yale Law was a place that really feels very self-consciously as the place that is the finishing school for American elites. Go to Yale, or you go to jail. You go to Yale, and then you—
DOSHI: I think many of us should be in jail, then.
WANG: Well, that is definitely true. But, you know, the Yale—you go to Yale Law, and you go be a staffer at the White House, maybe run the White House, et cetera. But there are some issues with rule by lawyers. Last night I took the Acela train down here from New York to D.C. And Acela has gotten an upgrade, gotten a refresh, where it’s the next-gen Acela. And this next-gen Acela is around eight minutes slower than the previous generation of Acela. (Laughter.) So this is where, you know, century by century, decade by decade, we’re not moving faster than we were in the past. We’re moving slower than the past. And this is where I feel like the United States used to be an engineering state. When I’m walking around cities like New York, you know, it really feels like we’re walking through the ruins of a formerly great industrial civilization that our grandparents’ generation built. And so this is where I hope that we can do a little bit more thinking about, you know, how do we build better, a little bit more like the Chinese.
DOSHI: Well, that’s very interesting. And I think there’s a zeitgeist now about American decline and American renewal, what it will take for the United States to kind of recapture some of that capability that it lost and that it continues to lose—on the Acela, for example. But I think one key concept in your book is this idea that China is an engineering state, but the United States is a lawyerly society, and that there are things that China does relative to the U.S. that are—that it just does better. I was wondering if you could dig a little bit more deeply into that concept for us, maybe help us understand what the difference is, why there’s a difference between the two systems, as well as what the difference is.
WANG: Physical construction. I think a lot of it comes down to having very extensive public infrastructure in China, as well as a very robust manufacturing base. And so the engineering state is my stylistic device to talk about how China has built these staggering amounts of all different sorts of, you know, you name it—high speed rail, roads, et cetera. So the engineers are very intent on building their way out of different problems. And, you know, my base case is that I think that, you know, China right now is around one-third of global manufacturing output. It’s about 30 percent of manufacturing. And five, ten years from now I would expect that China’s share of manufacturing will grow rather than shrink. I think it will grow. And so, you know, I’m on the record now, so let’s check back in in five years. Let’s see if it will grow. But my expectation is that it is some of these advantages of the manufacturing engineering state, this will become more manifest.
Last year China built about 300 gigawatts of solar alone. The United States built about thirty gigawatts of solar. China right now has forty-five nuclear power plants under construction. The United States has zero nuclear power plants under construction. And so once, you know, all forty-five nuclear power plants come online, you know, the energy costs differential will be even more in China’s advantage. For any sort of product that we care to name—televisions, shoes, whatever—there is kind of a, you know, city-sized concentration of people building these sort of products in China. So you have these gigantic concentrations of network effects, in places like Shenzhen, which makes drones and iPhones.
And so, you know, you can’t throw a stone at some of these industrial hubs and not hit a very talented engineer, very good line worker, really competent component supplier. That is, some of the best in the world—some of the best people in the world at building these sort of things. And now China also has a very competitive market, in which, I would say, at a first approximation, China is practicing capitalism red in tooth and claw more effectively, in many ways, than American firms are. And, you know, this is why you have dozens of major electric vehicle makers making very little profit, trying to chase a share of the Chinese consumer’s wallet. And so once you combine all of these sort of things together with the excellent public infrastructure, I am skeptical that, you know, a lot of this could unwind anytime soon. And I think that China will continue growing more dominant in every aspect of manufacturing, because there is just still a lot of tailwinds in China’s favor to keep doing well.
DOSHI: I want to stay with that theme for a second, and then I want to turn to what you might think has changed since you wrote the book. But just staying with your core argument, it’s interesting. I mean, you’re right. China’s built all this amazing infrastructure. But we’ve seen other countries that were also engineering state like. You know, you think about Soviet modernization going from a negligible part of manufacturing, and then losing their share of manufacturing after the October Revolution, and then surging through brutal means in the 1930s. Were they an engineering state? What was that that allowed the Soviets to build so much? What about Japan, either in the Meiji Restoration or in the period up to World War II? Were they an engineering state as well? And then in the U.S. case, everybody today talking about the AI datacenter buildout goes back and says, look to the railroads. But were the railroads built by an engineering state, or a lawyerly society, or something else entirely?
WANG: The U.S. used to be an engineering state, up until the end of the 1960s, when the engineers with American characteristics made too many mistakes. So we had Robert Moses tear apart New York. We had the Army Corps of Engineers dam essentially every river in the Western U.S. We had the Department of Agriculture spray DDT absolutely everywhere. And these all had pretty devastating consequences. Then what happened? Yale Law took over. Yale Law, and Harvard Law, really a lot of these elite law schools, banded together to have something like the public citizens movement, public interest movement, which you had people like Ralph Nader say: I do not want to serve in government. I want to sue the government.
And even today, you know, I’m at Stanford now. I was just talking to my colleague Francis Fukuyama. We are working on a capacity to—or, an initiative to increase state capacity in the U.S. He would say something to me like, you know, very few of my students want to work in government. And, you know, here, you know, in most elite law schools, I think that, you know, the idea is still that the highest calling is to sue the pants off the government rather than serve in the government. And I think there is something in the elite culture here that has gone off the rails. And I think that what we need to do is to build quite a lot more. That what the moment calls for is to meet our housing shortage, especially in bigger cities like New York, Boston, San Francisco, where rents are surging, to do a little bit better at building the housing. That we cannot achieve the green transition without some amount of construction. And so this is where we need to learn a little bit more.
And I want to be very clear that I am not saying that the United States needs to be just like China. I absolutely do not believe that. I think that within liberal democracies there are traditions within ourselves that are in place to meet the moment. So the city of Austin in Texas met, you know, people moving in during the pandemic with a giant housing surge of construction that beat the rents down. Texas is building a ton of clean technology, in terms of solar as well as wind. You know, Japan, Denmark, plenty of European countries have built high-speed rail, very functional cities, without resorting to Chinese methods. And so what I’m saying is that there are, you know, methods that fit within our liberal democratic traditions that we can draw on ourselves that we should scale to the rest of the country. We don’t have to be totally like China to achieve better manufacturing.
DOSHI: Great. Well, let’s turn now to the question of what maybe has changed since you wrote the book. Do you feel that China continues on the kind of trajectory you wrote about? That, essentially, they’re going to dominate manufacturing and technology, become basically a techno-industrial superpower that can’t be rivaled? And if they do achieve that, what are the implications for the U.S.? Or, conversely, are they likely to fail in that pursuit? Or will that pursuit simply not achieve the results that many fear?
WANG: The one proposition that I want to leave everyone with, this is my belief, is that I think that China will be the global leader in advanced manufacturing, maybe technology writ large. But it will not overtake the United States as the world’s leading power. So I’ve already spelled out how China is, I think, going to do better and better on all sorts of advanced manufacturing. It’s doing pretty well on AI as well. We can talk more about AI. But, you know, I also don’t believe that China will be the world’s leading power, because the United States is not just still a technology scientific superpower; it is also a financial superpower, cultural superpower, diplomatic superpower, things that I think China will not be able to easily replicate.
So here are a few things that have changed since I finished writing my book. After I left China at the start of 2023, I expected that the economy will really come back in a big way, as it did across most other places that stopped lockdowns. And that did not happen. So China’s economy is now still pretty sluggish. Investment growth has turned negative. China’s property sector has fallen by roughly 30 percent in terms of the value of the homes sold across the entire country. And the apartments, the homes, are the main savings vehicle for a lot of people. And so, you know, when that declines, people are much more nervous to spend. Consumption has been fairly weak. Youth unemployment is now approaching 20 percent. And so, you know, there’s all these ways in which China’s economy is, I think, surprisingly sluggish. In which that, you know, I would have expected much more attention paid to all of these, you know, economic weaknesses. And it’s slightly surprising to me that China has not done terribly well here.
DOSHI: So just maybe two quick questions.
WANG: Please.
DOSHI: Then please continue. But it seems like there’s two claims here. One is that China can be a techno-industrial superpower, but that doesn’t make you the world leading power. A second claim is that China has economic challenges that they are ignoring that have also undermined their ability to be a world’s leading power. Which of those two really, for you, is the more important of those particular explanations?
WANG: Both are true. So I think that, you know, China’s—how many people—how well is China’s, you know, most successful sectors doing? So, you know, what’s going really well are things like AI, a couple of manufacturing sectors, but how large is that as a proportion of the economy? You know, how many people work in the AI sector? It’s in the, you know, tens of thousands. How many people work in semiconductors? Well, it’s, you know, hundreds of thousands, perhaps a few billion depending on where you draw the line.
DOSHI: I think all those high-tech sectors might be less than 10 percent of GDP if you look at the Rhodium analysis.
WANG: Ten percent, 15 percent if you want to squint. But it is not a giant sector of the economy. But, you know, my fear is that, you know, if China has—is doing very well on you know advanced manufacturing, that is still pretty important. China has seventy million manufacturing workers. And, you know, China has all sorts of problems. You know, not just the sluggish economy right now. There’s also questions of the political system. Next year, top leader Xi Jinping will probably give himself—almost certainly give himself another five-year term. And, you know, aging autocrats easily get cranky. And I’m not sure that, you know, the decision-making capabilities of Xi is getting better as he ages. And, you know, how do you handle succession? I think authoritarian systems just have this—this is an unsolvable problem for authoritarian systems. As soon as you designate a successor the entire political system is thrown into confusion. And so, you know, who’s actually in charge here? And so there’s all sorts of political issues.
The anticorruption numbers, investigations, are still rising. Right now in the Central Military Commission, which is the high command of the military, there’s normally seven members. Now there’s just Xi and his enforcer. So, you know, he’s decapitated high command. That doesn’t sound really good to me. And then there’s also, you know, one broader thing that I’ve also slightly changed my mind on, which is, you know, demographics. So I’m pretty sanguine about demographics in China over the next fifteen, twenty years. But, you know, the cliff really will hit. And when I was back in China this year in May, you know, I am really struck at how, you know, people just are not that—are pretty disaffected and are not that eager to build families. So the national total fertility rate in China right now, according to the official statistics, is 1.0. By contrast, in the U.S. it’s 1.6. In Shanghai, China’s richest city, it’s 0.6. In Xintiandi, Jing-an neighborhood, you know, China’s richest district, Shanghai’s richest district, it’s 0.4.
And so, you know, I think that is a pretty strong indictment of the system, that people don’t want to build families. And, yes, the fertility collapse has been real across East Asia, but it’s been especially stark in China at its level of development. And so, you know, could China fix parts of these problems with immigration? You know, it doesn’t seem like there are that many young Chinese—that there are that many young Americans, or Nigerians, or French people that are banging down the door to move to China. China, 1.4 billion people, has one million immigrants. Ireland, six million people, has one million immigrants. And so, you know, there’s a supply issue here, there’s a demand issue here, but fundamentally, you know, the reason that I’m pessimistic about China is that I think that Beijing has not—does not have a vision of human flourishing that is attractive to the rest of the world, or even that attractive to its own citizens.
But because the manufacturing is so present, I am nervous that, you know, maybe the last thing that China achieves before hitting the demographic cliff is fully deindustrialized Germany or fully deindustrialized Ohio. And so even though, you know, there’s all sorts of these challenges that face China over the longer run—economy, politics, demographics—you know, the manufacturing is still very, very real. And you know that’s going to cause a lot of political problems for us if China is still continuing to get better at all sorts of manufacturing.
DOSHI: The only area where I might push back on that claim—
WANG: Yes, please.
DOSHI: Is that I wonder if it’s—you ended by saying China might deindustrialize everybody before these problems catch up with China. If that’s true, if other countries lose their industrial bases, how can they truly remain superpowers? Let me just maybe push the point a little further.
WANG: Please.
DOSHI: If we believe that industrial bases produce technological innovation or the capability to defend yourself in a military conflict, then the loss of industry, which takes a lot longer to recapture when it’s gone than it did to just retain it or improve it, it may be a thing that is an asset that you can’t—you can’t capture back in a short period of time. So, is there a world in which China wins by basically putting everybody else out of business, and the result is that they can leverage that for other purposes?
WANG: Yes. And that is my great fear right now, that our politics get worse even in the short term, not even in the in the medium term, as we lose manufacturing. You know, arguably that has already happened in parts of the American Midwest, in, let’s say, East Germany, which has lost industry. And then is now, you know, the base of support for AfD. And so—and, you know, there is a longer-term question of, you know, if we don’t have very much of a manufacturing base. But this is also where—you know, this is why I’m saying that we need to be much better at building, not just building of homes, because our cities cry for them, not just the building of public infrastructure, because that benefits all of us as well as the manufacturing base, but also the manufacturing base itself.
You know, I am very struck that we have lost, you know, so many munitions, which is something that you’ve written very well on, Rush. But, you know, we’ve shot something like a decade’s worth of Tomahawk missile production at Iran over the course of a month. And yet, we’re still not, you know, really building enough of this. Is this a China problem? Well, I don’t really think so. This is mostly our own problem. And so, you know, we need to still get much better at producing all sorts of things and not continue hampering manufacturing, which, unfortunately, there’s all sorts of problems that the tariffs have caused right now as well. And so, yes, let’s just be very aware that this is China’s big advantage, and now we need to meet the moment.
DOSHI: Is there—as you think about solutions then to that deindustrialization problem—we’ll stick with this, I think, theme for a little bit—how much would you weight U.S. protection or European protection as a part of the solution, versus running faster? And the reason I say that is, take munitions. There’s a lot of reasons why we have a problem with munitions that are not related to industrial production, but there are some related to industrial production. The lack of sufficient commercial producers who can operate as quickly as we’d like, or the fact that the primes essentially have cornered the market so, as a result, maybe you can’t get a Patriot body made the way you might if you put GM on the case. And as you may have seen, GM was able to produce one in twenty-two days.
So if you lose industrial capacity, can you build housing? Can you build munitions? Can you do any of those things? And is the reason we have disinvestment in those areas because China will put you out of business if you even try? Like, good luck trying to make pharmaceutical products, API or KSM, in the U.S., when China will undercut you on price. How do we solve that problem, the disinvestment problem?
WANG: Some degree of protectionism makes sense to me. I don’t have any strong views about the optimal level. China certainly was very protectionist in many ways as it grew. But there’s something else that China really did to really increase its manufacturing output, which is that it got American firms to build its industrial base for them. So in the 1990s the canonical example was Walmart. In the 2000s the canonical example was Apple. In the 2010s, it was Tesla. And so, you know, we saw that Beijing had all these debates, well, how much do we allow foreign investment?
And there have always been all sorts of protections that make it pretty difficult for foreign companies to have unfettered access to the Chinese market. But, you know, you had Apple through Foxconn employ hundreds of thousands of people every single year to build the world’s most sophisticated consumer electronic product. You had Tesla really try to, you know, build sophisticated vehicles. The Chinese had a term here. It was called, you know, catfishing, which you drop, you know, a highly sophisticated, predatorial firm into the midst, and that upgraded everyone’s—that made everyone else raise their game.
DOSHI: Foreign firm.
WANG: Foreign firm, that’s right. And right now, you know, I think that, yes, we have some degree of protectionism through the tariffs, as well as, you know, regulations that essentially ban Chinese electric vehicles from being driven on the roads here. But I’m not seeing enough effort to replicate the Chinese strategy of, you know, having more foreign investment, including Chinese investment, build more in the U.S. And so, you know, this is where I think, you know, we have to have much better joined-up thinking here. Tariffs alone will not guarantee American success. We also need to raise our competitiveness. And we need to do it by hook or by crook.
DOSHI: One way I look at this is to say that each political party has had one half of the solution. Some have said, let’s do a lot of investment in key industries, but they haven’t secured the protections that would allow those industries to scale. Others focus on the protections, but they don’t do the affirmative agenda that would actually invest in technologies of the future. And if you put the two together, perhaps you have something that looks a little bit more like the Chinese approach.
So let’s turn to Europe for just a minute, because you mentioned deindustrializing Germany. And maybe the big story that’s coming is going to be the China-Europe potential trade war. It may not happen. We’ll see. But Chancellor Merz and Emmanuel Macron put out a letter on Monday. And in the letter, they indicated the need—this is a letter to the EU Commission—a need to be able to have a quote—like, they didn’t call it this in the letter—but it’s been termed the “kill switch.” Essentially, an ability to reduce drastically Chinese exports to Europe, if China responds to European efforts to reindustrialize with rare earth controls.
The idea being, we want to take steps like China. China doesn’t want us to take those steps, so they’re going to hit us with rare earth export controls. And we’re going to just cut them out of the economy if they try. Now, that’s just a letter. It’s not yet a full EU Commission instrument. But it suggests a remarkable shift from where Europe was a year ago. So how do you think about where the China-Europe story is going to go? And what are the larger lessons? Because a big theme that you’re pointing to is China has enormous problems, but they might deindustrialize everybody, but for those manifests. Europe seems like ground zero for that question. How is this all going to work out?
WANG: China is already deindustrializing Germany. And I think that there is—
DOSHI: Ten thousand jobs a month, industrial jobs, are being lost in Germany right now. Four Volkswagen plants closed in the last year.
WANG: And, you know, there’s—the Germans are trying to come up with a political response. The challenge is that with the EU there’s a lot of distance from here to there. And we’ve been hearing about European efforts to really confront China in a much bigger way for five, arguably ten, years, that the Europeans have been very well aware of this. And so I will—you know, let’s see if this develops from a letter, blossoms into an instrument.
DOSHI: But you’re skeptical.
WANG: I don’t have a strong sense. You know, but my priors are that they have not done enough so far, and so there’s reason to be—there’s cause for skepticism here. I’m much more worried about the Europeans because I think that—I was just—I just spent a month in Europe. I was just speaking especially to the French. And my fear is that, you know, Europe is being—is fighting a two-front economic battle against two sides. You know, China on manufacturing, and the Americans on pretty much everything else. So when it comes to something like these big European successes like biotech, the Danes gave us Ozempic. But now, you know, who’s doing best at GLP-1s? It’s Indiana-based Eli Lilly. And so Novo Nordisk has not done terribly well.
In terms of financial services, the Europeans are falling further behind. In terms of software AI, Europe is not very much anywhere at all. And so the—you know, again, China is already deindustrializing Europe. And we are seeing, you know, deindustrialization is not just round zero for Europe. You know, Europe is also ground zero for, you know, the messier politics. So Le Pen is now the favorite in the betting markets to win in France next year. Perhaps AfD will do better than this small province in eastern Germany. But, you know, I am fearful that, you know, the politics will get much worse, and that will be the big restraint on Europe, you know, reindustrializing in a much better way.
DOSHI: So deindustrialization leads to populism, and that complicates governance, leads to a lack of proper policy solutions, and the cycle continues. That’s sort of one—
WANG: That’s the transmission mechanism.
DOSHI: You know, it’s interesting, because when the Chinese write about America’s failure to fix the problems that you identified—and this is something I’ve read a little bit about—they talk a lot about how the U.S. politics became much more focused on cultural issues and less focused on material issues. If there’s one constant theme in your book, it’s that we have to always look at the material foundations of the economy, the industrial foundations too, and look after them. I guess my question is, how does this all square with AI? So you mentioned that you think things have changed since ’24. One of the big changes is AI is in a very different place than it was in ’23 and ’24. Many are saying the U.S. economy is doing well. Others look at these same data and say, the U.S. economy is doing poorly. So how do you make sense of the U.S. datacenter buildout, the AI bet? Will any of this matter in the competitive trajectory between the U.S. and China? And, by the way, could AI help us reindustrialize?
WANG: I am—I think that I am an optimist on AI reindustrializing China.
DOSHI: OK. (Laughs.)
WANG: I’m not sure that I’m optimistic about—
DOSHI: Reindustrializing? They’re already industrialized?
WANG: They’ve lost a little bit, but they always want more. It’s never enough for them. So, you know, when I think about AI and reindustrialization, now China has seventy million manufacturing workers. The U.S. has about twelve million. I think it is much easier to strap GoPros as well as all the sensors on the Chinese heads rather than on the American heads. And, you know, China right now has deploys something like half to two-thirds of the world’s annual new robotics installations every single year. And so—and China speaks about—Beijing speaks about AI much more in terms of physical technologies. And so it seems like, you know, if AI is useful for reindustrialization, China actually holds all the cards here.
In AI land, where I spend a lot of time, in California, you know, there’s all these—like, the rhetoric on AI, you know, still is, you know, it is either going to disemploy all of us or it’s going to kill us all. What’s the sales pitch here? This is, you know, a sales pitch with, you know, Silicon Valley characteristics. It is very odd. And, you know, it is also very odd the apocalyptic religious tones that they imbue AI with. And there’s so much, you know, religious element here. You have Peter Thiel giving lectures on the nature of the antichrist also over there. Does that smell like, you know, winning on robotics to me? I’m not sure. I’m not sure. But here is where I am, an optimist on an element.
DOSHI: Yeah, I was waiting for that, because—(laughter)—it’s been half an hour and I’m not seeing the case yet.
WANG: I am still an optimist from California. So, you know, here’s an area in which I’m optimistic about, that concerns AI. On July 4, America’s 250th, I landed in Phoenix, Arizona. And I spent about ten days there—yes, in July—speaking to the Taiwanese community that are building semiconductors for America. This is the site of TSMC Arizona, in which I think that this is a really big success story. This is where, you know, both administrations hold half the cards. The TSMC initially announced a $12 billion investment in Arizona in 2020, during the Trump administration. And, you know, after the CHIPS Act, after the Biden administration passed this, TSMC has invested a lot more. And so in July TSMC announced that it is going to invest $265 billion in Arizona. Right now, fab number one has gotten going. Fabs two and three are ahead of schedule. They’re going to build nine more fabs, two R&D facilities, as well as packaging facilities.
And here’s the crucial thing, the families that I chatted with in Phoenix, they’re pretty happy to be in Phoenix. The Taiwanese live in much larger homes than they could in Taipei. They go shopping at Costco on the weekends. Their kids can go to ASU, maybe they can go to Yale or Stanford. And then some of the men go shooting on the gun ranges on the weekends too, because more of them have military training and then they enjoy doing that sort of stuff. And so, again, on America’s 250th, you know, this idea of the American dream still means something to these Taiwanese engineers. And, you know, as I’m reflecting more on the Taiwanese story, you know, which other country can get Taiwan to give away its most strategic technology? This is the most important hardware technology in the world right now. Which other country can get Taiwan to invest a quarter of a trillion dollars into the desert over there, and still have people pretty happy to take part in this big project?
Can the Germans do this? Can the French do this? I’m pretty skeptical. And so this is still an American superpower. And this is—we have some green shoots to build on. There’s a million ways to mess this up, because about a year ago ICE deported around 300 Korean engineers out of Georgia who were trying to build batteries for this Hyundai-LG joint venture. And so implosion is always an option. And, you know, we keep tending a little bit too close to these sort of things. And we’re messing up in all sorts of ways. You know, the tariff strategy, beating up on the allies, you know, how we’re treating immigrants who want to be here to build their lives, there’s a million ways that, you know, we can improve. So let’s improve, but also recognize where things are going well.
DOSHI: It does sound like part of your prescription here, if I could summarize a few of the themes—and I’m curious of how you’ll react to this—is, one, you want to see the U.S. be a bit more of an engineering society, not just an engineering state, and have our elite culture better understand and appreciate the material foundations of the economy. The second thing that you’ve called attention to is our ability to attract talent, capital, et cetera, from overseas. And there, it seems the U.S. superpower is its allies, right? Japan, Korea, Europe, Taiwan, India, Canada, Mexico, the U.K. China doesn’t have that kind of network. And so if you put those two together, a domestic agenda focused on investment renewal, reindustrialization, and maybe, you know, deregulation in a few areas that complicate productive capacity, and you marry that with an allied strategy that harnesses the best that each of our friends has to offer, do you think that combined strategy gives us a chance at being able to weather the second China shock, and whatever else is coming?
WANG: Yes. And I think that it is really great, Rush, that you’re working so hard on this, especially with the China Strategy Program here. And I think that, yes, we need to engage more with the allies. And, you know, there’s some—yes, we need to attract better immigrants, and more immigrants. And so—and there’s one other leg that I would say—add to this. Which is to, you know, have more people move here. So, you know, when I’m walking around in the AI labs in San Francisco, you know I see that quite a lot of folks, you know, maybe, like, a third, maybe even half the folks, have Chinese heritage. Many of them are Chinese nationals. Many of them attended Chinese universities. There are many more people from Russia. And, you know, there’s something that China and Russia has that fewer American students are interested in, and that is math. Mathematics. We don’t do that so much anymore here. But the, you know, Russians and the Chinese are still very eager to do that here.
And, you know, part of what I’ve been saying is that, you know, maybe we’re winning on AI right now because our Chinese are better than their Chinese. So why don’t we get more Chinese, and more of their Chinese, and more of their Russians, too, and have them here in the U.S. building their lives? Let me put a little bit more emphasis on that strategy because something else, you know, to just to bring it back to China a little bit, is that so many folks in China have been deeply freaked out about what’s going on. High net worth individuals—
DOSHI: Right? We should talk about this. Yeah, what’s going on with the taxation policy?
WANG: They are reaching into the pockets of many people to say, we want your taxes. So after the collapse of zero COVID, after, especially, the collapse of real estate sales, a lot of local governments have become more stressed about finding revenue. And so, you know, they’re going up to rich people in different provinces. They’re going up to rich people in their own provinces to say, you owe us some taxes. And then the business people would say, OK, how much? And then the tax bureau would say, you tell us. And so, you know, there’s all the sorts of these—
DOSHI: It actually reminds me a bit of how India sometimes handles tax issues, right, in big companies. It shakes them down sometimes for this revenue bump. Not exactly great for creating a stable business environment.
WANG: Not exactly a sign of, you know, political confidence, that this is what they’re doing. And they’re, you know, going after these Singapore trusts, and then saying, you know, we’re going to exert some overseas taxation now. So a lot of people have been pretty deeply freaked out in China. You see that, you know, there’s these figures that I quote in my book. You know, something like 14,000 millionaires left China in 2024. They’re taking their money to Singapore, London, Hong Kong, or maybe more, like, New York, because they are really deeply nervous about what’s going on in China.
And within all of these different sectors, after these thunderclaps that Beijing dealt towards tech firms in 2021—you know, Jack Ma’s Alibaba is still—the market value is still half its peak in 2021. And so there’s a lot of people who are pretty eager to leave. And so this is where I’m thinking, you know, why are we so mean to—in the Trump administration—especially to South Asians? That’s, like, public enemy number one. But also, you know, East Asians, as well as others. Sorry, Rush. (Laughter.) But, you know, this is—we don’t have to be doing so poorly. Public enemy number one, public enemy number two. You know, we don’t have to do so poorly here.
DOSHI: (Laughs.) I was just thinking, a lot of nationalists who watch this panel of an Indian American and Chinese American talking about—Canadian, excuse me—talking about our problems and say, isn’t this the issue? It’s the two of them, right?
WANG: Well, maybe the Canadians are the public enemy number one now.
DOSHI: Canadians are number one, right, yeah. Well, look, I think, Dan, this has been fascinating. We have about twenty-two minutes left. I want to turn to the audience for Q&A. We’ve got people in the room, people online, and a lot of questions. So we’re going to take them in batches. If you could be brief with your questions, that way I can get more in, all the better. And, Dan, if you could be brief with your answers. Up here in the front first.
Q: Thank you. Bob Grady, your partner at Summit Partners, and actually vice chairman of the Hoover Institution at Stanford.
I want to return to—
WANG: My boss, thank you. (Laughter.)
Q: We work for you. No. I want to return to the topic of AI and AI strategy and competition. You mentioned tens of thousands of AI workers in China. Clearly, the Chinese have adopted sort of a strategic model that one might call diffusion, of sort of relying on open source and open weight models, and at a much lower cost than the American Frontier models. Qwen, I think, threw off, you know, hundreds of derivative models from—just from that individual model. Whereas the U.S., you could argue, with heavy reliance, both in terms of capital and even businesses relying them, on OpenAI—on the models produced by OpenAI and Anthropic, and the let’s call them the exquisite models. So maybe U.S. performing a dominant strategy, China a diffusion strategy.
A, how does that roll out competitively? Do you think that puts China at a great advantage as more companies and people use AI for discrete business cases throughout the society faster? And, B, what do you think the strategic risk to the United States would be about—with respect to having more of reliance on open weight and open source models, and not being so reliant on the exquisite frontier models?
DOSHI: It’s a great question. I think we should add to that the financial sustainability of the current U.S. model, and whether or not we are at risk of some kind of crisis. Maybe put a pause in that for a second. Any other questions? We got another one in the front. I’ll work my way back in due course. But want to—up here as well.
Q: Mark Kennedy with the Wahba Initiative at New York University.
You talk about that we’ve got Silicon Valley, but they got Shenzhen. They got these pools of engineers concentrated in an area. You maybe saw that beginning in Arizona. Do you see in the robotics area there’s any way we can get the Detroits and Clevelands of the world back into their engineering states? And do we need to concentrate these clusters, like Shenzhen?
DOSHI: Great question. And then one other here, and, yeah, that table in the middle. Thank you.
Q: Dan, you put a huge emphasis on manufacturing.
DOSHI: If you could just—I know you are, but—
Q: Oh, Nick Lardy, Peterson Institute.
You put a great emphasis on manufacturing and China’s strength, but it’s only about 40 percent of the economy. Services are way over half. And services have been the major source of growth in China for the last five years. So could you say something about how you see the service sector?
DOSHI: OK. So, Dan, we got three questions. One on AI diffusion versus the U.S. model, and if you’ll add—if you’ll indulge me, the financial sustainability of our model. Second from Mark, you know, can we create industrial scale and clusters like China? Should we do that? And from Nick, of course, services.
WANG: Services are great in China. You know, anyone who can walk around in Shanghai—and I expect to do that soon—to, you know, go to some of these cafes, noodle shops. You know, it doesn’t seem like this is a low-consumption society to me. They are very awfully robust. But, you know, I take these sort of more economic views of the sort held by Brad Setser, that people are nervous to spend. That, you know, maybe there should be a better social safety net. There should be better provision of healthcare safety, safety in—certainty in healthcare. And so, you know, China just hasn’t had enough propensity to spend. Maybe you disagree with that, Nick. But there is also pretty substantial youth unemployment. And so, you know, they are just not consuming quite as much as they produce. And so I think it would be better for China, as well as for the rest of the world, to, you know, have a little bit more robust consumption as well.
When it comes to industrial clusters, I think the U.S. approach, I think, is not making these concentrated industrial bets. It is still a little bit more about regional development initiatives. And I think that there should be more concentration, rather than less. You know, when it comes to semiconductor production, it doesn’t all have to concentrate at Silicon Valley, but there’s a—you know, there’s a Micron fab going up near Syracuse. There’s, you know all sorts of stuff happening in Ohio. You know, there’s all sorts of ways to say, well, these regions have fallen behind, and so we’re going to try to, you know, save them through by putting in a factory here. Whereas I think the better approach should be to identify our strengths and then double down on them, rather than trying to, you know, patch up these sort of weaknesses. I’m not seeing enough in that direction.
DOSHI: What about the AI diffusion question?
WANG: You know, I think that we can debate a little bit about what are the motivations with China’s open weight models. You know, maybe it makes sense for China to lean so much in on open weights because they are behind, that there is some degree that China relies upon distillation. And that, you know, makes sense, because China is compute constrained, to offload more compute elsewhere. And so maybe that is a lot of what is motivating China. If the Chinese models somehow become ahead of U.S. models, I’d be a little bit skeptical that they would still be allowing this to diffuse quite a lot. You know, U.S. is still diffusing AI pretty widely. There’s a lot of enthusiasm from corporates to use AI, sometimes in ways that are not very smart. And so, you know, they’re demanding on a lot of employees to go use AI. And, you know, employees are, you know, checking the time with AI, and just having all these, you know, not very—pretty silly projects to fulfill corporate demands. But there is an effort to diffuse in the U.S. as well, just as there is in China.
You know, what works? Too soon to tell. And, you know, the extent to which—my issue with U.S. AI strategy is that this is so much focused on making better models, and I wonder the extent to which, you know, just having somewhat better models is really all that useful at the moment, if we’re not so much focused on, you know, trying to diffuse it through our society and really trying to reindustrialize with the robotics as well, because, you know, I’m not sure that, you know, something like Mythos—I don’t need Mythos-class models to answer my email, or figure out my trip planning. You know, there has to be a little bit more joined up thinking here. Where in China, you know, they want to have the models. They also build the datacenters. And they also build the power facilities, which is less evident here.
Is this a financial—is this financially sustainable? You know, I don’t take a very strong view on this. You know, after speaking to folks in New York, you know, everyone would concede there’s all sorts of shakiness with AI models, the pursuit of AI right now, because there’s questions about sustainability. You know, there’s a datacenter backlash throughout the rest of the country. So there’s all—there’s Chinese competition, in which, you know, some of these token costs from China’s open weight models—I’ve heard estimates of, you know, Chinese costs could be something like 1/130th the cost of Anthropic, 1/150th is also a number that I’ve heard. So the Chinese models are definitely much cheaper. And so you notice all sorts of shaking here. On the other hand, the AI companies are blowing the lights out. And the corporates are incredibly excited about using AI. And you can see the revenue growth of firms like Anthropic doubling. And so, yes, this feels like, you know, we’re really trying to steer a rocket ship here. There’s all sorts of ways this is going wrong, could go wrong. But so far, you know, a lot of things have turned out pretty well too.
DOSHI: Let’s take some questions from online.
OPERATOR: We’ll take the next question from Fred Hochberg.
DOSHI: Hey, Fred, can you hear us?
Q: Thank you. Yes, I can hear you. You talked about deindustrialization, which leads to populism, and, if I recall, a focus on economics. A lot of what I’ve read about populism is people feeling a lack of respect, a lack of recognition also being a driver of that. I don’t know if you can comment on that, or if that plays a role in your thinking here.
DOSHI: Great. We’ll take another question from online, if we have one.
OPERATOR: We’ll take the next question from David Kirkpatrick. And there are no other questions at this time.
DOSHI: Thank you.
Q: Thanks. Can you hear me all right?
DOSHI: Yes, we can hear you, David.
Q: When I read your book, I came away with sort of a grim view of both countries, sadly. And you’re sort of reflecting that again here today. But not long before your book was published, Ezra Klein and Derek Thompson published Abundance. It was a huge bestseller. It’s sort of an ostensible, at least, movement of abundance in the U.S. And I just—it does seem to be addressing some of the central critique that you make about our country. And I’m just curious if you think that there is any kind of sort of significant shift in attitudes towards the kind of prescriptions that you have recommended.
DOSHI: Great.
WANG: Yes. I am a card-carrying member of abundance. I spoke at the Abundance Conference last September here in D.C. I’m for abundance. You know, this just seems, to me, to be the answer that, you know, we need to—you know, if we have a little bit more construction, as well as, you know, more investigations into our procedural emphases, you know, I think that we should be able to, you know, solve a lot of our problems. And I think abundance is doing quite well. There has been some movement on the permitting front, which makes it completely impossible to build a lot of big projects in the U.S. And I am hopeful that this can continue doing better. There is some green shoots of construction, even in New York City, because people—you know, Mayor Mamdani is quite interested in building. So, yes, we definitely see these sort of green shoots. And this is also where I am slightly more optimistic about the U.S. in terms of the ability to self-correct.
You know, President Trump has had a lot of unpopular policies. And I think he will hear about it in less than a month from now at the ballot box. So that is an element of self-correction. We are having more construction of many different things. We have TSMC Arizona. You know, there’s all sorts of ways in which we have these green shoots, and we are responsive to needs. And, again, we have a fairly—you know, an economy that looks pretty shaky. There’s all sorts of uncertainties here. But it is still growing pretty well. China does not really have these sort of things. The U.S. has people that want to build families and have kids. China has many fewer of that. U.S. is still a very attractive place for a lot of ambitious people to move to in the world, including from China.
So, you know, ultimately, I think that—you know, call me a liberal if you must—but, you know, I am, you know, pretty—I am happy to have moved here at the start of 2023, because what I craved above all else was some degree of pluralism. That there are people debating these different issues, that I am able to present my views, and some people can hear them and debate them and disagree with them, if you wish, but that we are able to have these sort of discussions. That is much more challenging in China. So, yes, I am a little bit grim about the U.S., but I think that there is a lot of strength. And, you know, I like that the questioner brought up this issue of respect. This is also something quite challenging to work on.
Again, I’ve been working a little bit with Frank Fukuyama. You know, he has this idea of thymos, in which this is—people crave respect in society. This is to some extent slightly zero-sum in terms of distribution. We can’t have, you know, universal recognition of everyone. So this is one of these sort of things that is, you know, by structure, challenging. Frank’s memoirs also, which just came out, also got into this. I’m not sure how to fix these sort of things but, you know, I wonder if there is a way still to, you know, make everyone feel, you know, welcome, and good, and, you know, respected in in some big ways, because we haven’t done very much of that in many parts of the U.S.
DOSHI: OK. Let’s take some more questions from within the room. Maybe in the back over there, I think, Ishaan.
Q: Thank you. Hi there. Ishaan Tharoor. I’m the Murrow Fellow here at CFR and columnist at the New Yorker.
My question is, I think, the other side of David’s question, to a certain extent. You know, it’s been really striking seeing some of this Pew data this year, the polls that indicate that global public opinion around the world is more in favor of China than in the U.S., and across a wide geography. You voiced in your remarks a kind of skepticism about China’s ability to project genuine soft power. An engineering state, an autocratic state, is not a state that you associate with soft power. But is China—I mean, where does soft power fit in the Beijing imagination at this point? And what would it take for China to have a genuine soft power moment?
DOSHI: Yeah, great question. Maybe here in the front, this table here in the center. Yeah.
Q: Thank you. Klaus Larres, UNC Chapel Hill.
Could you comment on the geopolitical situation right now? We had that summit between Xi and Trump, and things seem to be going very smoothly. On the other hand, we still have competition, rivalry, South China Sea, Taiwan, the nuclear race, you name it. So are we having a romantic relationship with China or are we going to war with China? Thank you.
DOSHI: (Laughs.) Or something in between, perhaps. (Laughter.) All right and then other question right here in the front as well.
Q: Thank you very much. Jeannette Chu, National Foreign Trade Council and CSIS. Good to see you again, Dan.
I’d like you to address if you could, please, you talk about there’s still much more capacity for Chinese manufacturing. Where does overcapacity fit into your calculus? Because, as you’ve noted, China has struggled with trying to boost consumption now for decades, and that’s not going anywhere. So they’re not going to be able to internally spend their way or buy their way out of all this manufacturing capacity. And now they’re being targeted by the U.S. and others about overcapacity. Thanks.
DOSHI: I want to try to get a few more questions because I think this will be our last round. Do we have any questions online? No. All right. So back in the room. Hands up. All right. Maybe in this middle table here, and then the last one in the back corner.
Q: Hi, thank you. My name is Kirsten Asdal. I run a China risk advisory firm.
Do you see any relationship between China’s fixation on manufacturing and the weakness in the rest of the economy? And, similarly, the increase in manufacturing output and the increasing weakness in the rest of the economy? Maybe even similarly, the idea—the conviction that they can engineer a soul, but they’re having less souls than ever born. (Laughter.)
DOSHI: Maybe they can’t engineer aggregate demand. All right, in the back over there, last one.
Q: Hi. Thanks so much for doing this. Mary Brooks, Scale AI.
I’m curious if you could go a beat more on rare earths, and how the kind of chokepoint leverage that China has is actively affecting U.S. industrialization efforts and European ones, and whether or not you think that the actions that are currently being taken are going to be sufficient to kind of flip that dynamic, or whether this is like a longer-term problem.
DOSHI: OK. I think it’s as many questions as we can take. That’s five. That’s a lot. Let me restate them very quickly. From Ishaan, we have the question of soft power. Interestingly, the Chinese are more popular than we are, despite having limits on their ability to promote their own soft power. From Klaus, we have the question about the geopolitical competition in the relationship, including after the summit. Another question about overcapacity and how we think about that in the Chinese context. And then a question about, can manufacturing focus cause weakness in the larger macro economy? Are there tradeoffs that China is putting off because of its obsession with manufacturing, perhaps the extension or overextension of credit to manufacturers? And then from Mary Brooks in the back, rare earths, are they stopping reindustrialization and can we fix that problem? You want to start with—
WANG: Rush, I’ll put you on the spot, what’s your briefing about the geopolitical summit?
DOSHI: Well, you know, people are here to hear you, not me.
WANG: No, but—
DOSHI: On the summit, I’ll just be very quickly. Very symbolic. Very little on substance. Stabilize the relationship for a bit. No big progress on many of the questions of the day. Both sides want to buy time. The question, as your book helps us understand, is who’s going to use that time better. And as Mary’s question gets at, the rare earths piece is alive. I mean, in January, this trade truce will be up for renegotiation. Will the Chinese provide enough rare earths? The U.S. government says we’re only getting two-thirds to one-half. Will the U.S. raise tariffs or increase import controls and export controls in response? That’s a live option.
So I think we have a moment of calm, another summit in November and December, but come January three things happen. One, the truce expires; two, there’s no more summits to keep things calm; and, three, the situation with Europe could get much, much stormier. So I think ’26 was stable because ’25 was bumpy. I think ’27 could be bumpy because ’26 was stable. But let’s go to the other questions. Maybe soft power?
WANG: I think it was Greg Ip who said that, you know, China now is—Trump now is the biggest panda-hugger in D.C. And, you know, he’s the biggest Canada hawk also. So, you know, there’s something very strange with these sort of alliances.
DOSHI: That is strange, yes.
WANG: With respect to soft power, this is not—you know, the rest of the world being more fearful and disliking the United States, that’s not just a Trump phenomenon but that is, in part, a Trump phenomenon. If, you know, you tell the rest of the world that we’re going to elect a normie Democrat, I think that that is—I think, will repair it somewhat, but not the entire thing. I’m skeptical that China can engineer much soft power, just as I think that it cannot engineer more births. You know, you can’t coerce copulation. That is just not possible. You can do the one-child policy, which imposed around 300 million abortions over thirty-five years, 100 million sterilizations of women, twenty-five million sterilizations of men. It is really difficult to turn that switch back on. I think that China will not engineer soft power, because engineering is antithetical to soft power.
And, you know, so, yes, there is some extent to which there are young Chinese who are—young Americans who are going to Chongqing to Chinamaxx, and looking at these big buildings, and subway systems, and, yeah, that’s really, really fun. But I will believe it once, you know, we have more Chinese—I’m sorry—more Americans studying Chinese at American universities than Korean, which is right now the case. And once we see more, you know, young people really adopting—
DOSHI: That’s a good optic.
WANG: Yes. If we see more Americans really hankering to move to Chongqing, I’ll be wrong here.
And, you know, with respect to overcapacity, you know, the Chinese will say there’s no such thing as overcapacity. You know, we are just building so much, and if the rest of the world wants to buy don’t punish us for following comparative advantage. This is slightly difficult to tease out what exactly it means, but I think now I’m just taking it as a given that China is just, I think, structurally—just structurally has to tend towards overproduction rather than underproduction. There’s just so much competition here. They say they want to rein this back in, but, you know, this is mostly private firms trying to build more auto facilities. And Beijing seems at least slightly reluctant to play central planner once more, to say, well, you, BYD, can have another auto facility, and you, Xiaomi, cannot. And so, you know, there is just all this way—all these ways in which that China just really, really wants to produce quite a lot more.
And then finally, on rare earths, this is, again, something I am actually slightly optimistic about for the U.S. Now I spent a little bit of time at the facility that MP Materials has in Fort Worth, Texas building magnets. And, you know, magnets are coming out of the factory right now. The Mountain Pass Mine is outside of Las Vegas, and it is on the California side of the border. In the 1950s, this mine produced 100 percent of the world’s rare earth supply. It’s just a really easy mine to extract materials from. Now, there’s a question about whether—you know, actually might be the case that most heavy rare earths are fully in China, within China’s borders. That’s just how the cookie crumbled. But, you know, for light rare earths, that’s actually pretty well distributed throughout the world. This is why you have all these announcements that Japan discovered more rare earths, Chile discovered more rare earths.
But the U.S. has some refining capacity here in the U.S. The magnets are not that difficult to make. And, you know, there’s—my only question is, you know, how many chokepoints does the China have really on the U.S.? Even if we solve this rare earth issue, is that one of five chokepoints China has on the U.S.? Is it fifty? What if the number is 500, and we have to do 500 times what we did to MP Materials, which is partially nationalize the company through the Pentagon and then have these price offtake agreements to, you know, have basically a price floor to prevent Chinese dumping? If we have to do this 500 times, do we really have the capacity to do something like this?
What I’m wondering about is, does the U.S. government even really understand all of these dependencies on China? You know, when I ask around, you know, someone would say, well, you know, there’s parts of the Pentagon that’s mapping this out, there’s parts of Commerce that’s mapping this out. But do we really understand these sort of chokepoints, until China really decides to squeeze? And so, you know, here’s where, you know, I’m maybe optimistic on one chokepoint, when the Chinese revealed it to us, but do we even understand where all the chokepoints are?
DOSHI: Well, that’s a great place to leave the conversation. Thank you very much, Dan. Thank you all for joining us. (Applause.) Let’s give him a round of applause. Thank you very much. I believe there’ll be lunch outside for those who care to partake. Thank you very much.
(END)
This is an uncorrected transcript.