The Import Cut Beijing Did Not Order
How has China imported less oil amid major supply shocks and war in Iran, and what does it mean?
By experts and staff
- Published
 Zongyuan Zoe LiuCFR ExpertMaurice R. Greenberg Senior Fellow for China Studies
Since what the International Energy Agency calls “the largest supply disruption in the history of the global oil market” arrived in late February this year, China—the world’s largest crude oil importer with 90 percent of its imported crude arriving by sea—has not scrambled to bid for every replacement barrel. Instead, China sharply cut its crude imports. By June, four months into the supply disruption, China had cut crude imports to the lowest level in nearly a decade. China’s ability to endure the Hormuz stress test shows Beijing’s decade-long efforts to build buffers and reduce dependence on oil as fuel have changed the pressure points of an oil supply disruption on its economy and society. How the Chinese government manipulated the shock transmission mechanisms and which part of the Chinese economy absorbed the shock are instructive for assessing China’s strategic vulnerability and its preferred costs allocation approach in times of crisis.
The scale of China’s reduction in crude imports is striking, but Beijing did not directly order the cut. It views the Hormuz supply shock not purely as an energy security problem but as a macroeconomic stability challenge. Its priority is to prevent rising oil prices from cascading into imported stagflation for good reasons: the Chinese industrial system could withstand lower crude imports, but its demand-constrained economy could not withstand the wrong kind of imported inflation, where prices rise due to higher oil prices rather than rising wages.
The Chinese political system and its policymakers are also more tolerant of, and more capable of, an industrial adjustment problem that can be diffused among a concentrated number of state-owned and independent refiners than of the political consequences of a broad and visible increase in higher costs of living imposed on hundreds of millions of households at a time when social stability is under mounting pressure because of weak employment opportunities and stagnating wages.
Hence, Beijing took its well-versed supply-side approach to prioritize domestic supply and compress rising costs largely within its refining system. As crude prices started to increase rapidly in early March, the Chinese government first restricted refined products exports to ensure domestic needs. Within a week, it raised regulated retail fuel price ceilings in the sharpest increase since 2022. When prices surged above $100 per barrel by late March, the Chinese government increased regulated price ceilings again, but by less than its pricing formula would have allowed, avoiding the full pass-through of the oil price increase to domestic consumers. China has a long-standing administered pricing system stipulated in the Petroleum Price Management Measures, which limits how much and how quickly rising costs could be passed on to domestic gasoline and diesel prices.
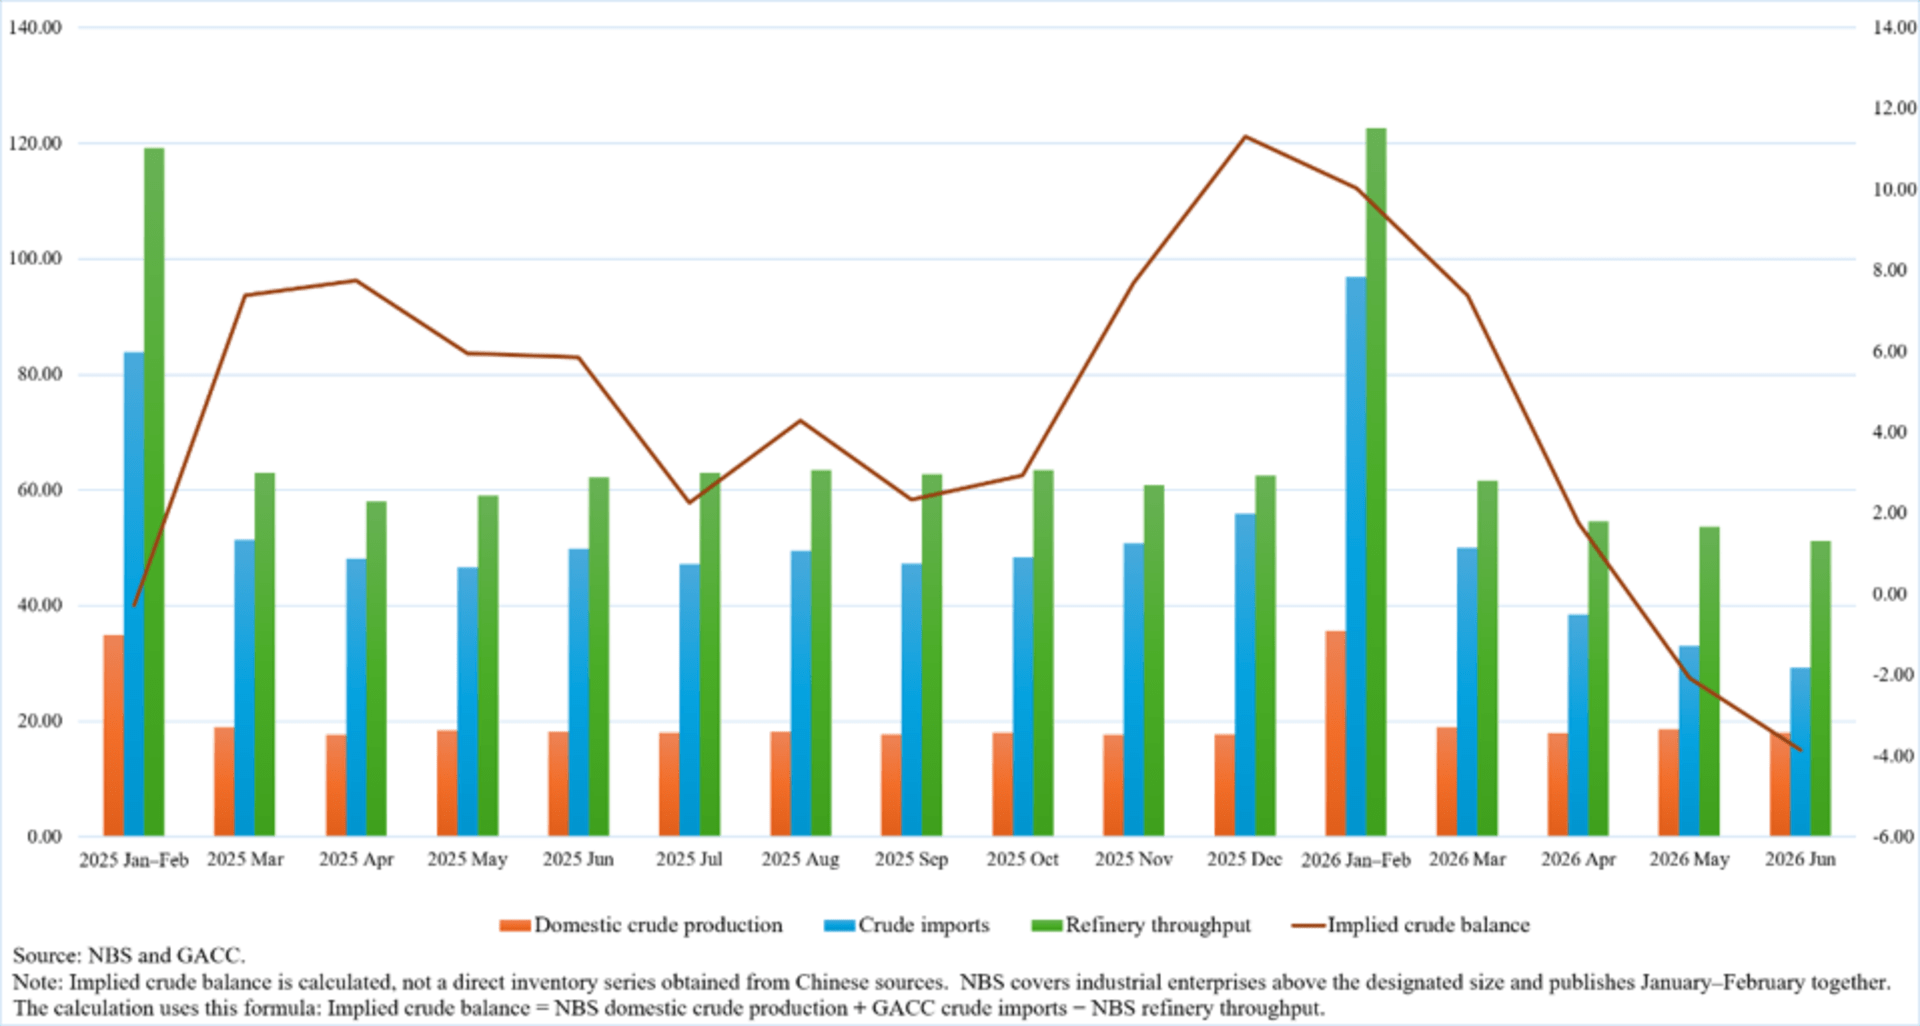
Beijing’s approach meant refiners were expected to maintain refining production, forgo profitable export markets, and sell products at home where demand was weak and price increases were capped, which would squeeze refiners’ profit margins with rising crude prices and diminishing inventories. Refiners seek to maximize profits. When market conditions and government policies turned against them, they adjusted to minimize losses by reducing crude imports and cutting production. They took the counterintuitive measure of not rushing to replace missing barrels amid a supply shock thanks to prewar inventory buildup, China-bound Gulf crude secured before the Hormuz disruption, and deliberate import diversification. Inventory availability provided the initial buffer for refiners to absorb the shock by slowing down stock accumulation. China entered the disruption holding an estimated nearly 1.4 billion barrels of commercial and strategic crude, roughly 120 days of imports at its prewar pace. At the macro level, these inventories allow Beijing to sustain at least a three-month-long import cut on its own terms without allowing the supply shock to force a sharp domestic economic contraction. At the refiner level, these stocks mean that refiners can wait and do not have to rush to replace disrupted Gulf barrels with expensive spot purchases from other supplies. Customs data on crude imports and National Bureau of Statistics data on domestic crude production and refinery throughputs suggest inventory buildup slowed from January to April, and refiners did not have to draw down inventories until May and June.
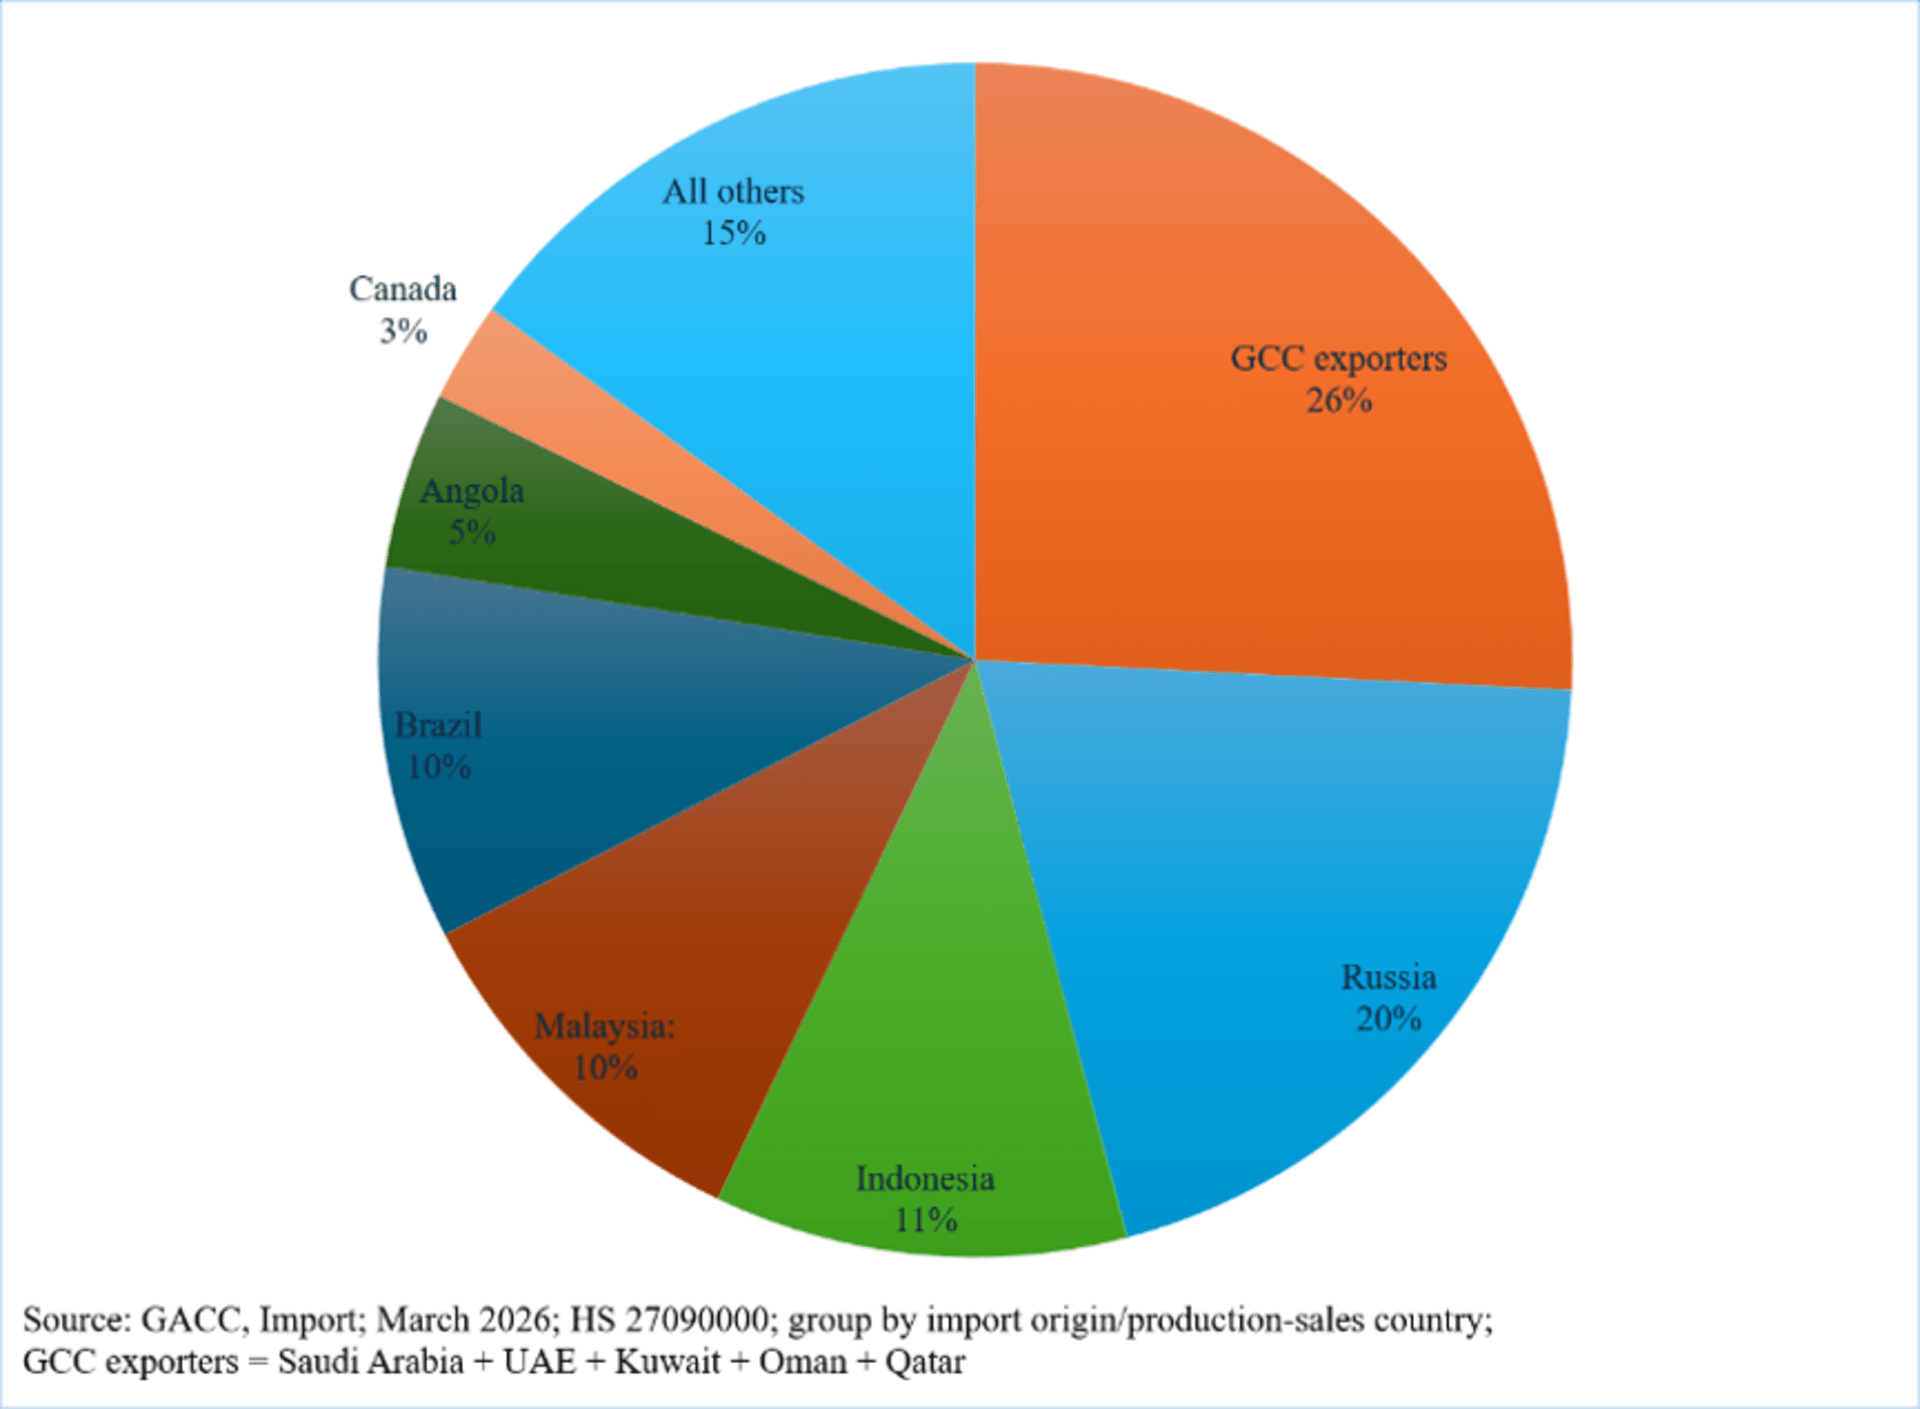
The expected arrival in March of Gulf crude secured before the Hormuz supply disruption and China’s deliberate import diversification from non-Gulf exporters provided an additional buffer for already well-stocked Chinese refiners so they did not have to panic buy. In March, Middle Eastern crude destined for China loaded before the Hormuz disruption continued to reach China after a typical 20–25 day voyage. Chinese customs recorded 122.6 million barrels from six major Middle Eastern suppliers in March, namely Saudi Arabia, Iraq, UAE, Oman, Kuwait, and Qatar, accounting for about one-third of China’s total crude imports that month. China also received Iranian crude at the pace of about 1.71 million barrels a day in March, according to Kpler, or about 53 million barrels during the month. Chinese customs data does not directly show imports from Iran, but it may likely be reflected in oil from Malaysia and Indonesia carried by their shadow fleets. Malaysia, Indonesia, Russia, Brazil, Angola, and Canada together provided almost 60 percent of Chinese crude imports in March.
As refiners retreated from the spot crude market, China’s oil imports declined sharply even though Beijing did not order the cut. During the second quarter, China’s crude imports decreased from prewar levels by about one-third, from an average of 12 million barrels per day during the second half of 2025 and sustained through February 2026 to an average of 8.1 million barrels per day. Imports bottomed out at 7.12 million barrels a day in June. This means during those three months China bought roughly 355 million fewer barrels than it would have if it had maintained its prewar pace, equivalent to almost one month of normal Chinese crude imports, or roughly 180 fully loaded supertankers. But refiners did more than cut imports. To avoid having their profit margins squeezed too much, they have also adjusted their refining operations in response to rising crude prices, higher freight and insurance costs, falling inventories, and government restrictions on refined products exports and price increases. Refiners did not wait to cut production until having to tap into cheaper inventories. Even though crude secured before the Hormuz disruption continued to arrive in March, refiners had already begun cutting throughputs to preserve existing inventories. March refinery throughput fell to 61.76 million tons (about 14.6 million barrels a day at 7.3 barrels per ton), down 2.2 percent from a year earlier and well below the roughly 16.3 million barrels per day of crude available from imports and domestic production combined.
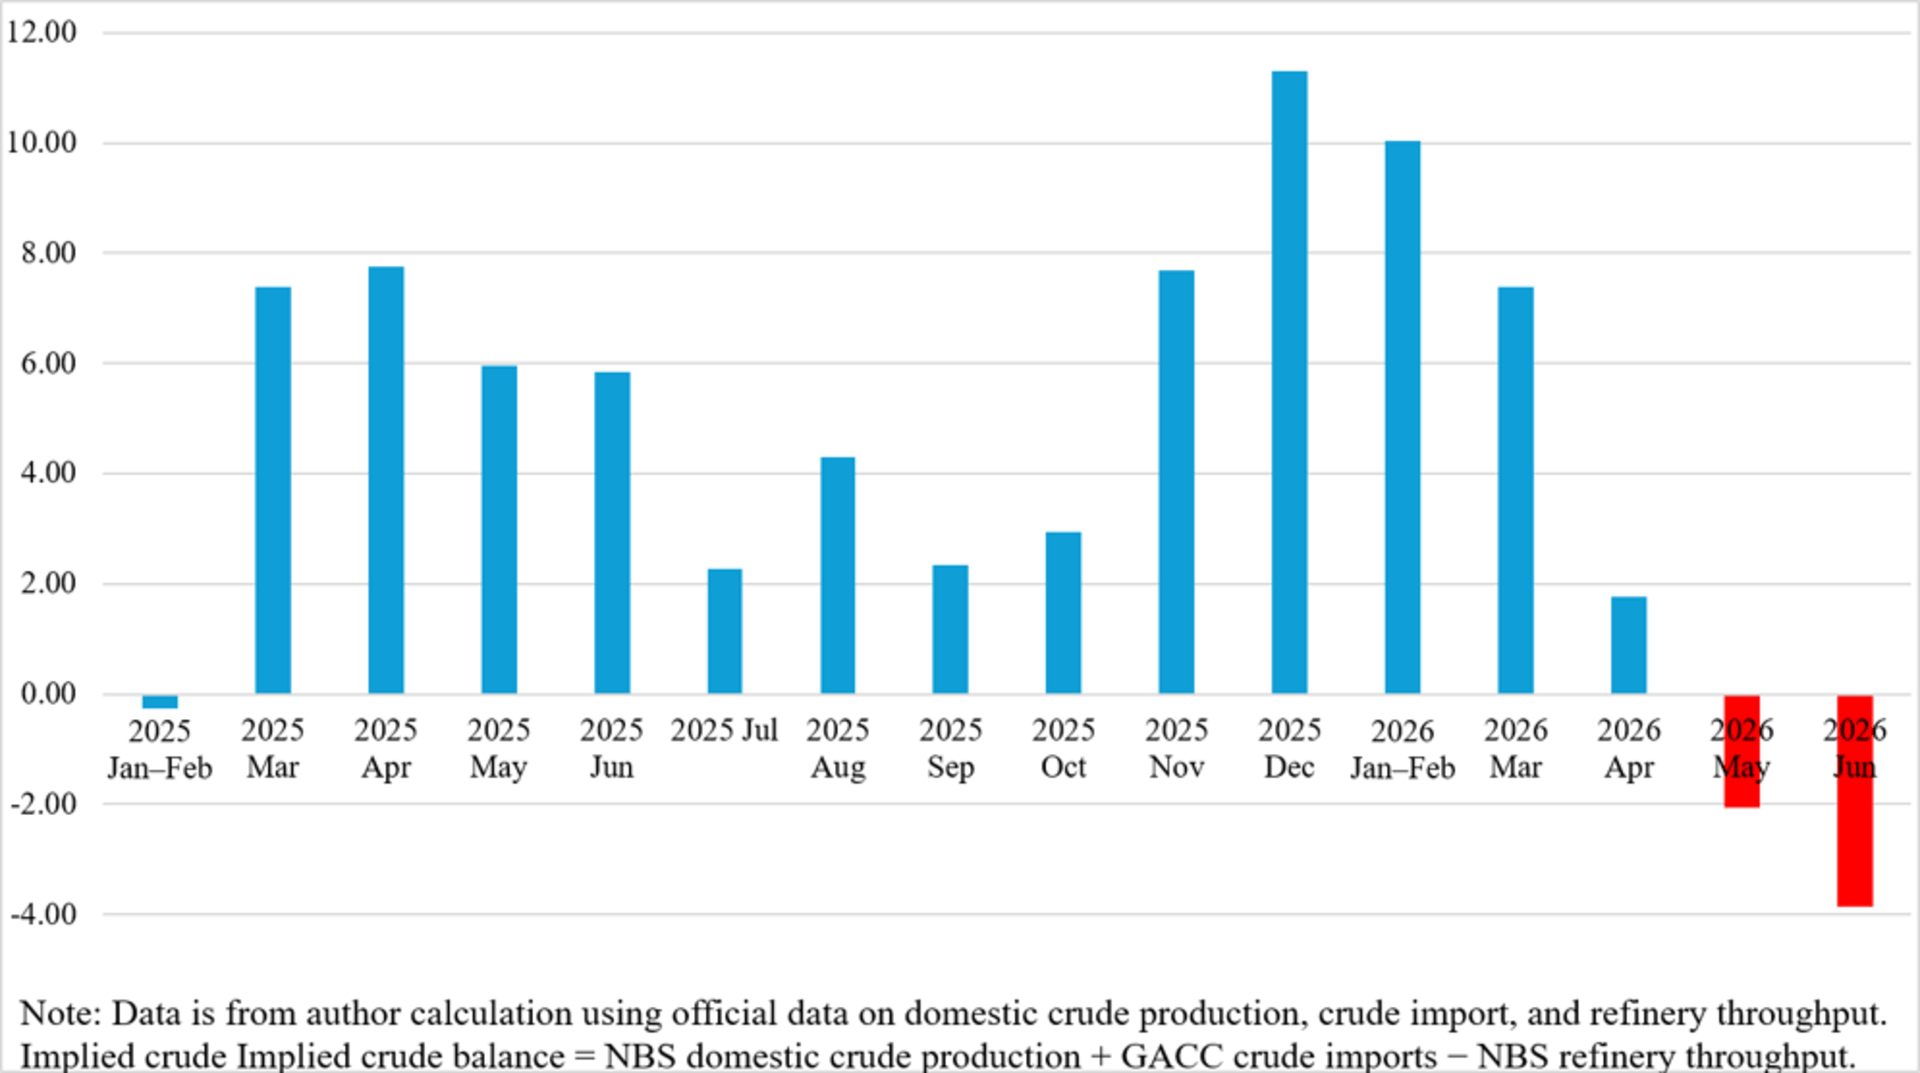
As cheaper oil secured before the Hormuz disruption ran low, refining margins were further eroded, making it even harder to maintain production. For independent refineries whose margins depend on discounted crude, especially teapots in Shandong, the more crude they refined, the more money they lost. At the worst point in April and May, Shandong teapots were estimated to be losing over 1200 yuan (about $175–$180) for every metric ton of crude they processed, equivalent to a negative refining margin of roughly $24–25 per barrel. Thus, refiners cut throughput even further. NBS data show that refinery throughput contracted sharply through the second quarter, despite the NDRC already instructing independent refiners at the beginning of April not to cut throughput, otherwise risking their crude import quotas being slashed. Some private refiners also sought Beijing’s approval to cut production.
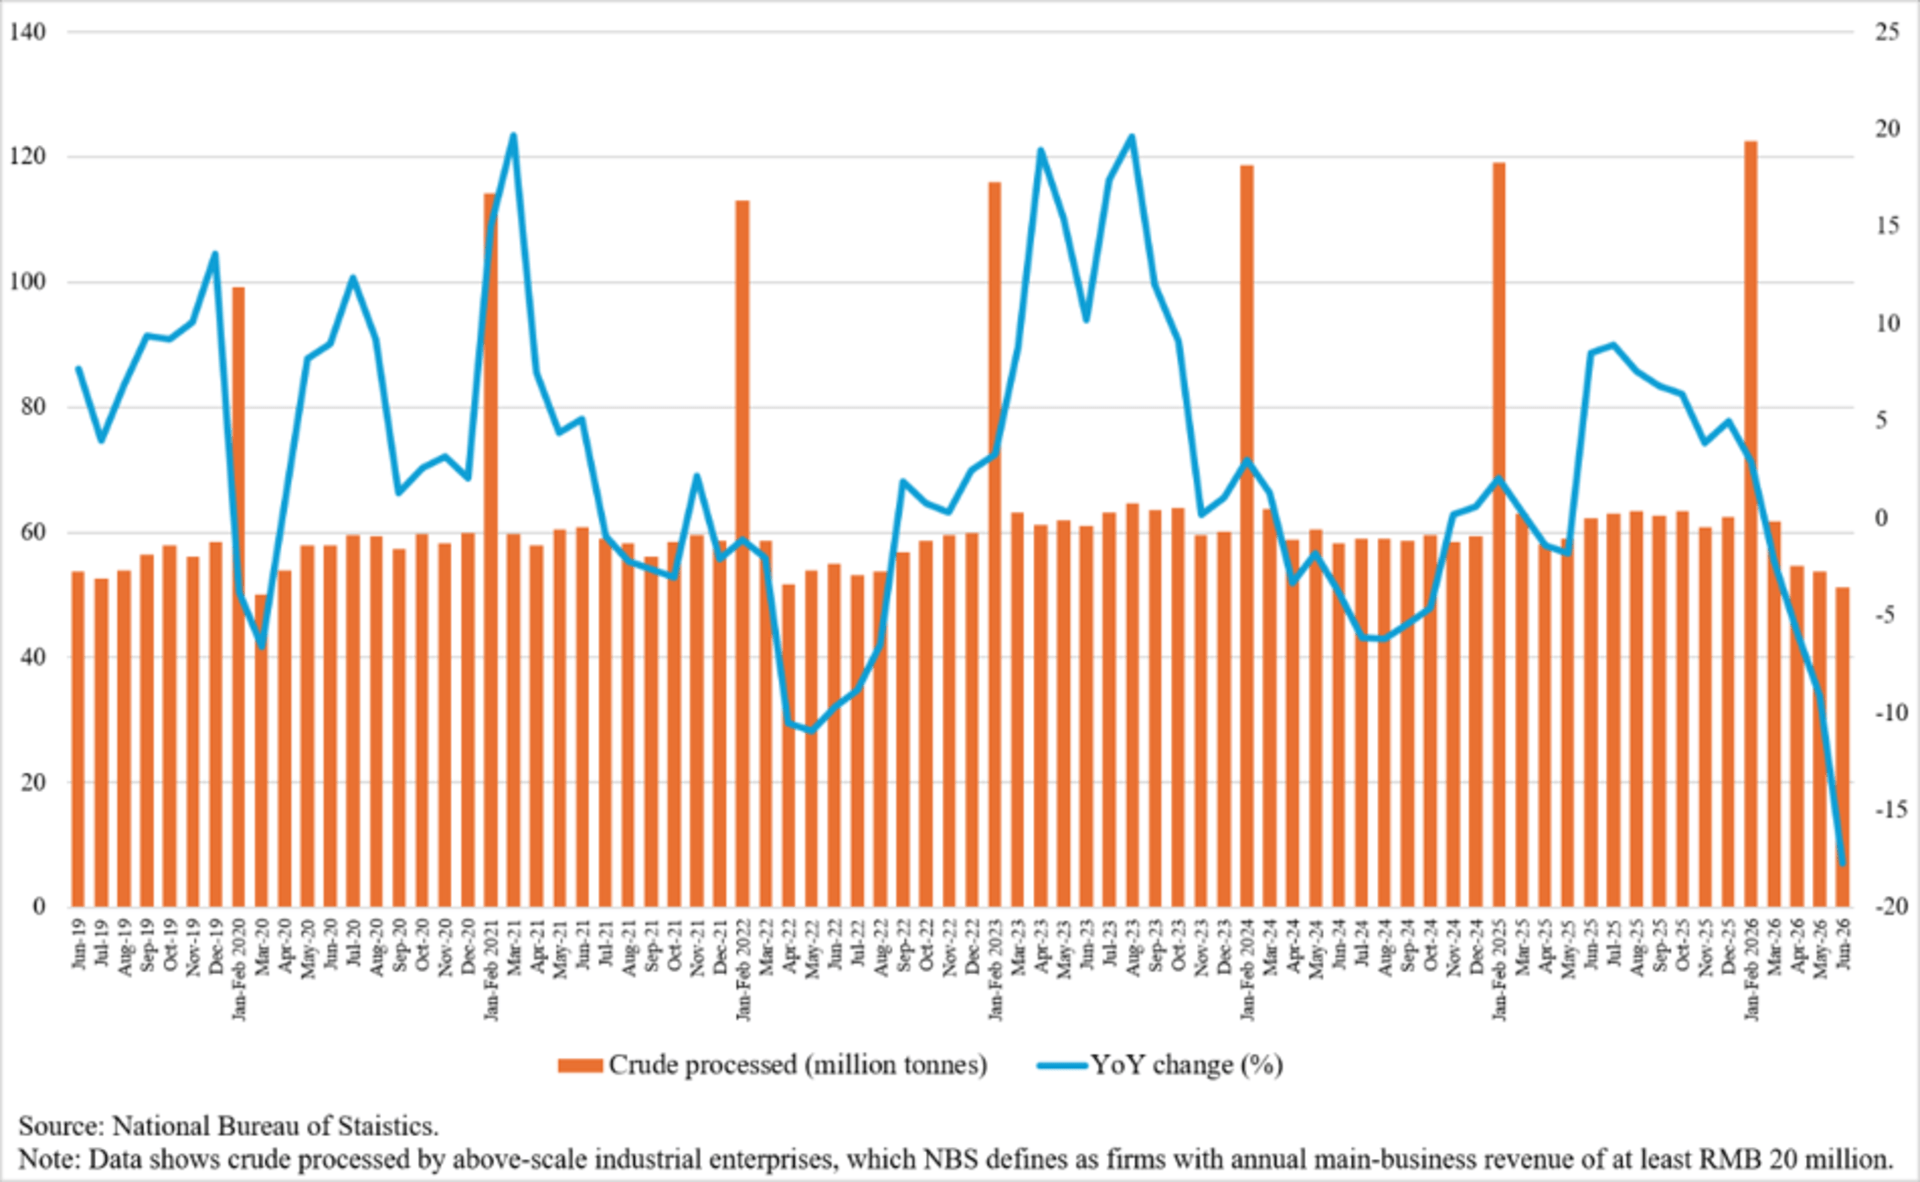
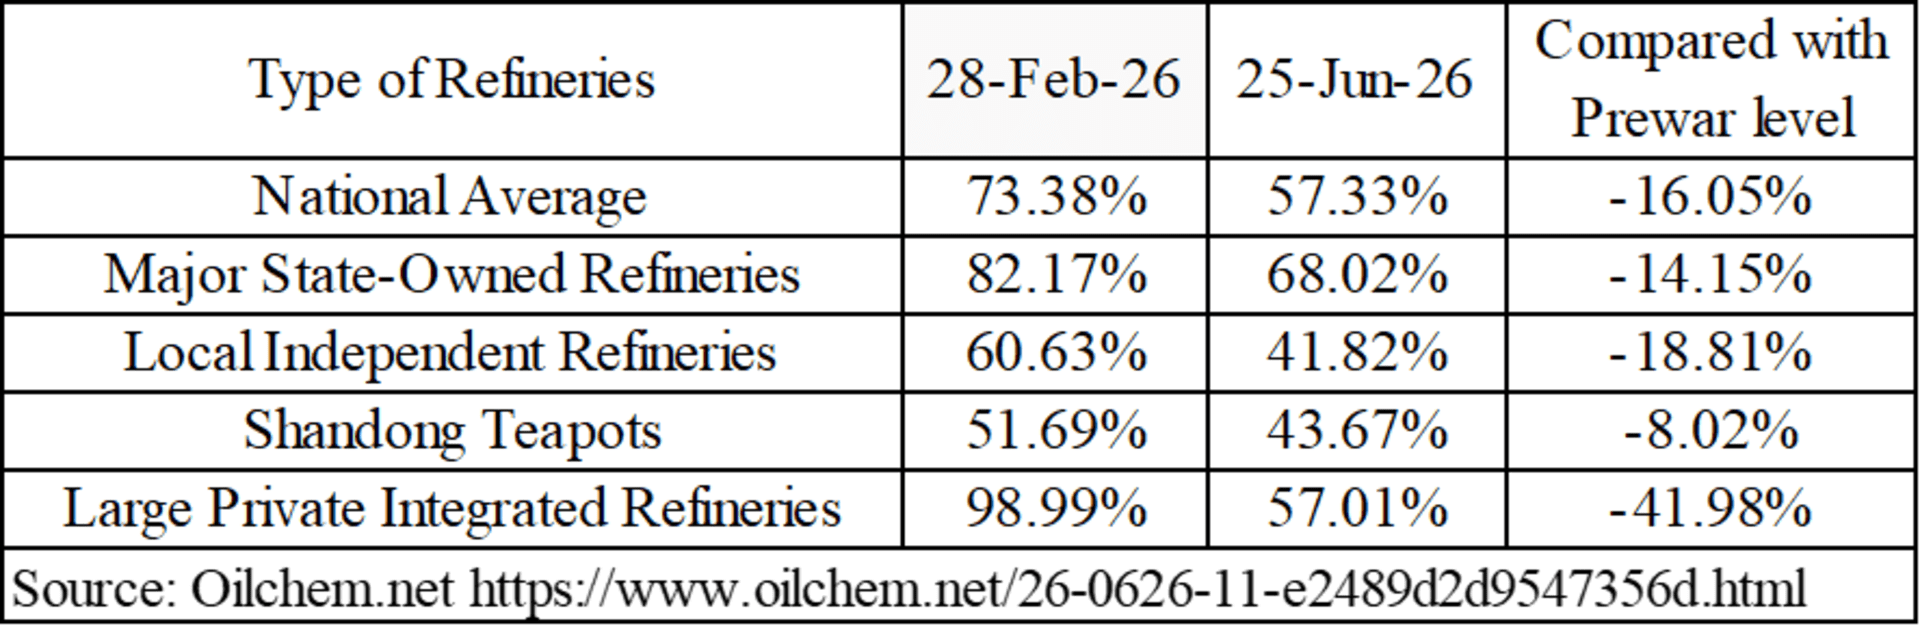
By the beginning of June, Chinese authorities allowed some loss-making Shandong teapots to moderately cut output to no less than 80 percent of the 2025 levels. By late June, Chinese refinery throughput slumped to its lowest level since the COVID-19 pandemic. All types of refineries had cut production to lower than prewar levels, although different types of refineries cut at different speeds and magnitudes. Local independent refineries slashed production to the lowest level since the outbreak of the COVID-19 pandemic in March 2020. State-owned refiners owned by Sinopec, PetroChina, and CNOOC cut production lower than their own bottom during the COVID-19 pandemic.
Thus, by concentrating the Hormuz shock downstream at the refiners, the Chinese government induced, not commanded, a sharp crude imports contraction. China’s reduced crude imports have generated the positive externality of sparing the rest of the world from an even more severe price squeeze. The U.S. Energy Information Administration concluded that China’s lower imports reduced global demand and softened the upward pressure on oil prices created by the Hormuz disruption.
When Chinese refiners return to the spot market and restart stockpiling, their deferred purchase demand could push up crude prices, especially if their return is faster than oil production recovery in the Middle East due to the destruction of oil production facilities and infrastructure during the war. To avoid bidding up prices in a tight physical market and undermining their profit margins, Chinese refiners are likely to return gradually and opportunistically, rather than rush to replace all lost imports and inventories.
A more structural reason why Chinese refiners are unlikely to snap back is that they are in no rush to raise throughput, as China’s domestic baseline fuel demand has been structurally reduced by the electrification of the transportation sector. Beijing views electrification of the transportation system and reducing fuel dependency as an integral part of its energy security plan. In April 2025, the Ministry of Transportation, together with nine other central government agencies led by it, issued a national policy on integrating transportation and energy systems and set targets to increase electricity use and green-fuel production capacity in transportation with the stated aim of strengthening national energy security. The 15th Five-Year Plan reinforces the same approach, calling for faster substitution of non-fossil fuels in transportation. The government’s electrification drive allows the nation’s transportation system to draw on its entire multi-source power system rather than directly on gasoline or diesel. Even as China builds the world’s largest clean energy system and clean energy generation is increasing, coal still provides about half of Chinese electricity. Domestic coal provides the ultimate backstop for China’s discretion over crude imports.
Encouraged by policies, China is accelerating the substitution away from petroleum in transportation wherever technology permits. In the first six months of 2026, China’s existing EV fleet is estimated to have displaced about 1.35 million barrels per day, or 6 percent of China’s total annual crude imports, a rate that would approach 12 percent if sustained through the year. This structural reduction in fuel demand was equivalent in scale to about one-third of the roughly 3.9 million daily unbought barrels in the second quarter. Lower baseline fuel demand could allow refinery cuts and inventory draws to stretch further without immediately forcing a fuel shortage.
The substitution extends beyond road vehicles to rail, inland shipping, and air. China’s 50,000-kilometer high-speed rail network and more than 11,000 kilometers of urban rail provide electric alternatives to road travel and some air travel. By the end of 2025, China had deployed 623 pure battery-powered vessels, a 42 percent year-on-year increase. In April 2026, China deployed the world’s largest pure electric smart container vessel that is expected to save 580 tons of fuel a year. Its size is comparable to a standard regional feeder cargo vessel and can travel on a single battery swap. As more modes of transportation adopt electrification, each future crude supply disruption will confront a somewhat smaller underlying petroleum demand, and Chinese refiners will have more room to cut crude imports and lower throughput before shortages reach consumers.
But electrification does not eliminate crude oil demand. Rather, it has shifted China’s oil demand growth away from fuel to petrochemical feedstocks. This change has transformed the nature of China’s vulnerability to high dependence on oil imports. An oil supply shock is increasingly not a fuel shortage problem but an industrial adjustment problem, one that Beijing can manage through supply-side policies that diversify the raw materials used by the petrochemical industry, in addition to oil stockpiling and refinery output management. Thus, reduced fuel dependence has given China more room to manage its exposure to oil supply disruptions before shortages reach consumers.
Refiners are at the center of this transition. Modern large Chinese refiners are increasingly operating as integrated refining and petrochemical complexes. In addition to processing crude oil into gasoline, diesel, and jet fuel, they produce petrochemical feedstocks such as naphtha, a light liquid used to make basic chemicals. Since 2018, Chinese refiners have begun adjusting their operations in anticipation of declining fuel demand growth and petrochemical demand driving crude demand. The Chinese government has encouraged this transition from refining to petrochemicals. In 2022, Chinese authorities formally incorporated “reducing fuels and increasing chemicals” into its industrial policy for the petrochemical industry during the 14th Five-Year Plan Period. Petrochemicals are intermediate industrial inputs to make auto parts, electronics, consumer goods, and other higher-value-added goods. A prolonged shortage of petrochemical feedstock could spill over to downstream industries, raise production costs, erode manufacturing margins, and even force production halts and layoffs.
Coal chemicals give refiners another source of flexibility during a crude supply shock by providing an alternative route to some of the same basic chemicals, although they cannot fully replace petroleum-based petrochemicals. Coal can be converted into synthesis gas and methanol and then into olefins such as ethylene and propylene, the building blocks for many industrial inputs that would otherwise be made from naphtha. China has been deliberately developing this coal-to-chemicals pathway. In 2017, the NDRC formalized a plan titled “Layout Plan for Innovative Development of Modern Coal-Chemical Industry,” explicitly calling for expanding, not replacing, the sources of petrochemical raw materials to reduce the petrochemical industry’s high dependence on oil and gas imports. China’s industrial policies have since continued to promote refinery integration and the orderly development of modern coal chemical industries.
Before the oil supply disruption, China already had meaningful coal chemicals production capacity that could provide some relief when crude and naphtha-based petrochemical plants face feedstock supply disruptions. In 2025, China produced 15.45 million tons of coal-derived olefins, accounting for 15 percent of total national olefin production, and its production of coal-derived ethylene glycol reached 7.62 million tons, or about one-third of total national ethylene glycol production. These volumes cannot eliminate Chinese industrial demand for petroleum-based basic chemicals, but their existence means that a reduction in refinery throughput does not translate proportionately into a shortage of basic industrial inputs.
During a crude supply shock, coal chemicals relieve some pressure for refiners to maintain high crude runs simply to meet downstream demand. They could cut naphtha and concentrate production on products with fewer substitutes. Meanwhile, coal chemicals compete with the petrochemical output of integrated refiners. High crude prices weaken the economics of increasing refining throughput to produce additional feedstocks. When crude prices increase, naphtha crackers become less competitive relative to coal-based olefin producers. The average coal-derived olefin production costs were estimated to be about RMB 6,800 per ton (or about $993 per ton at the exchange rate of RMB 6.85 per USD) in late March and April, compared with roughly RMB 10,700 per ton (or about $1,562 per ton) for oil-based production, giving coal chemicals a cost advantage of over one-third.
This trend is directionally consistent with previous NDRC estimates in 2022. When oil prices surged in early 2022, average coal-to-olefin production costs were RMB 7,596 per ton (or about $1,130 per ton at the 2022 average exchange rate of RMB 6.729 per USD), compared with RMB 9,600 per ton (about $1,430 per ton) for oil-based production. The NDRC attributed this gap partly to the different cost structure. It estimated that naphtha accounted for roughly 75 percent of the production cost of oil-based olefins, whereas coal accounted for only about 22 percent of the cost of coal-derived olefins. This means the economics of naphtha-based petrochemicals are much more sensitive to, and directly tied to, crude prices than those of coal-to-olefins producers.
Thus, recovery in refinery runs is likely to depend more on fuel margins, inventory needs, and government supply requirements than on crude availability alone. As long as petrochemical economics do not improve, Chinese integrated refiners have little incentive to increase throughput, and that reduces the urgency for them to return to spot purchases even as more oil becomes available.
Electrification and the refining-to-chemicals transition are changing how an oil supply shock is transmitted through the Chinese economy. They give the Chinese government more room to use its preferred supply-side tools to respond to a supply disruption. They also allow China’s demand for crude as fuel and as chemical feedstocks to be cushioned by domestic coal. Future oil shocks may be less likely to trigger an immediate energy crisis in China and more likely to unfold as a managed industrial contraction, with Beijing attempting to compress the costs among refiners and industrial producers before the shock produces the wrong type of inflation driven by higher prices not higher wages. Chinese refiners may have greater capacity to cut imports during a future supply shock, despite China’s high dependence on oil imports. An import dependence ratio alone is therefore an incomplete measure to evaluate an economy’s vulnerability to an oil shock. What is at least equally important is how deeply a country can cut imports, and for how long, before an oil supply disruption spills over into industrial damage or the resulting costs become intolerable.
This work represents the views solely of the author(s). The Council on Foreign Relations is an independent, nonpartisan membership organization, think tank, and publisher, and takes no institutional positions on matters of policy.